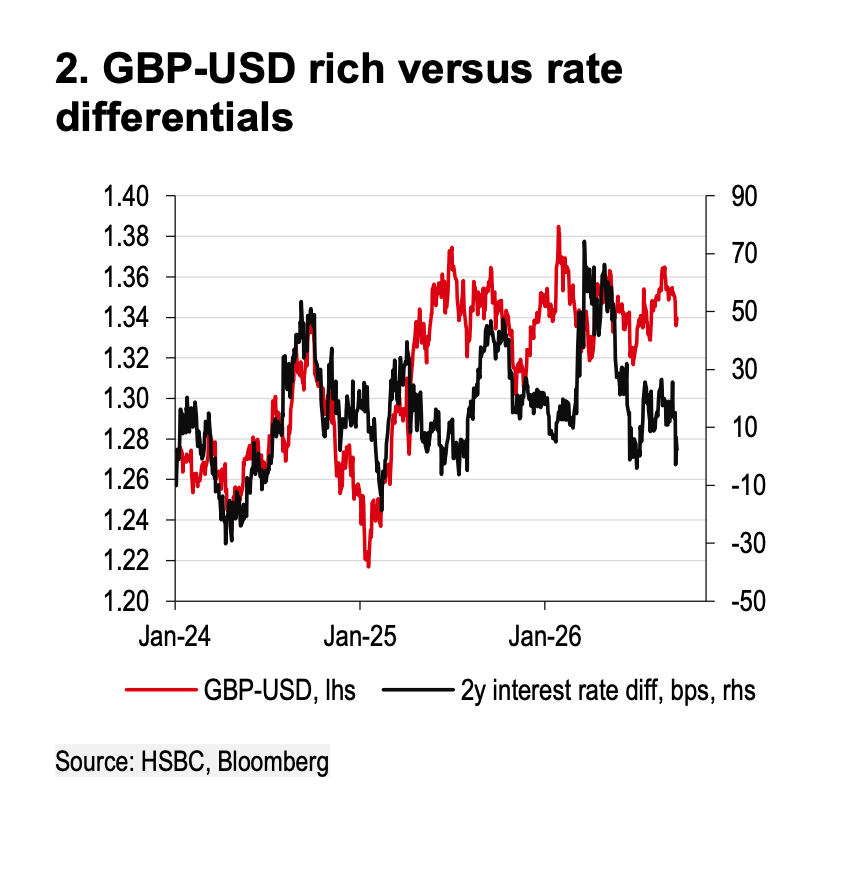
📝Sterling Flags Rich vs Differentials: HSBC
Weak UK labour demand and sluggish private sector momentum could weigh on the GBP in the near term, particularly as the US economy is looking more resilient. Markets are already pricing around 100bp of tightening from the Bank of England by July 2027, but higher energy prices create a difficult policy mix: inflation risks are rising even as growth momentum faces a challenging outlook. The run-up to the budget update on 28 October may add further pressure, with elevated gilt yields (Chart 2) and difficult fiscal choices ahead for the new Chancellor.
We expect the broad USD to strengthen modestly in the near term as cyclical, political and structural forces turn more supportive or become less of a headwind. The key question is whether US rate expectations will remain firm relative to those elsewhere. However, energy-price resilience and a broader reassessment of fiscal risk should also favour the USD at the margin. We look at two currencies where we think the USD has the upper hand. - HSBC

Comments